You enjoy many options when shopping for permanent life insurance. It's possible to get coverage that lasts for your entire life (as long as you continue to pay the required premiums and other costs), ensuring a measure of protection for your beneficiaries upon your passing.
Two popular choices are universal life and whole life. Here's a closer look at one versus the other as well as insight into important questions, such as "can you cash out whole life insurance?" and "is one better for you than the other?"
What Is Whole Life Insurance?
Whole life insurance is a permanent insurance contract with a guaranteed death benefit and cash value. As long as you pay the premiums required for coverage, the insurer will provide the benefits promised. Premiums are typically fixed for the life of the contract, which helps provide predictability as you manage your budget.
The cash value in a policy earns a fixed interest rate, which is guaranteed when the policy is issued so that you can anticipate your cash value in any given year.
What Is Universal Life Insurance?
Universal life insurance is a form of permanent coverage that offers some flexibility. As long as you pay the costs of insurance, your policy can remain in force for your entire life.
This type of insurance also provides policyholders with a cash value. The crediting rate on a universal life policy's cash value can change, so you often can't predict how much you'll have in cash value. Rates typically depend on economic conditions and interest rates, and the insurer can adjust rates over time.
What's the Difference Between Whole Life & Universal Life Insurance?
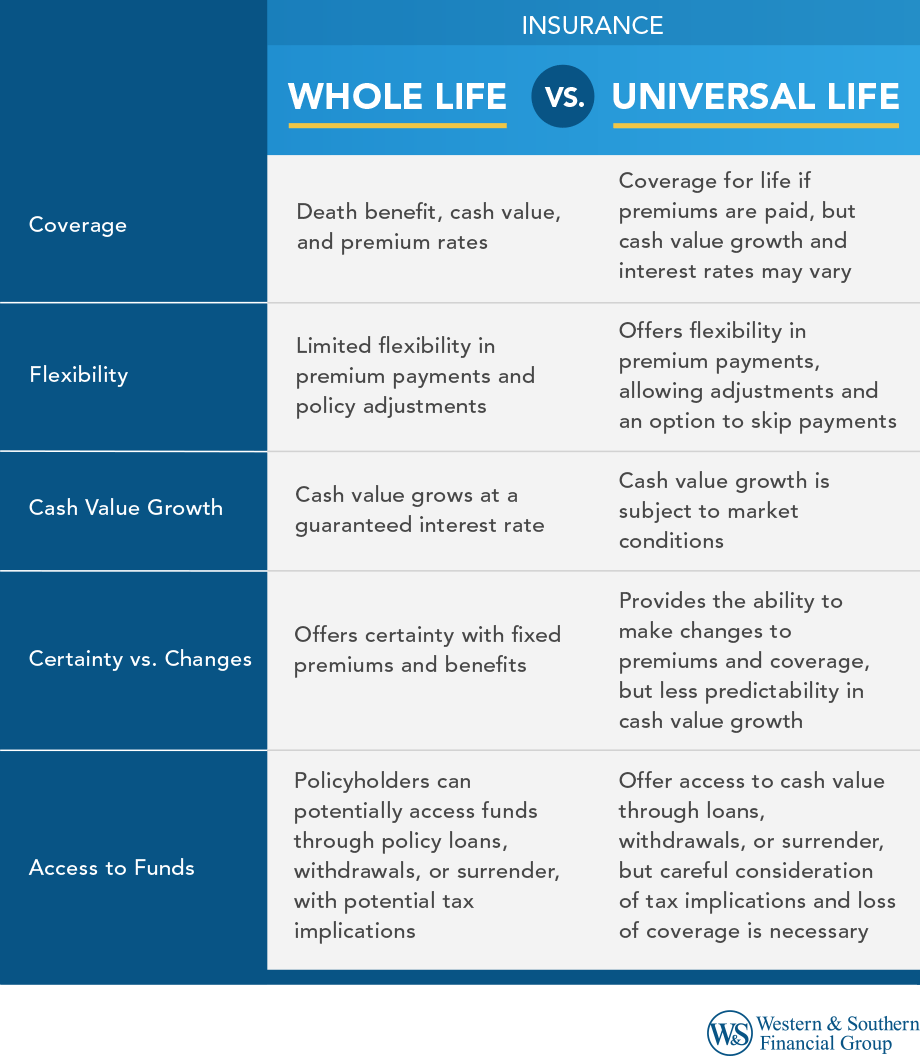
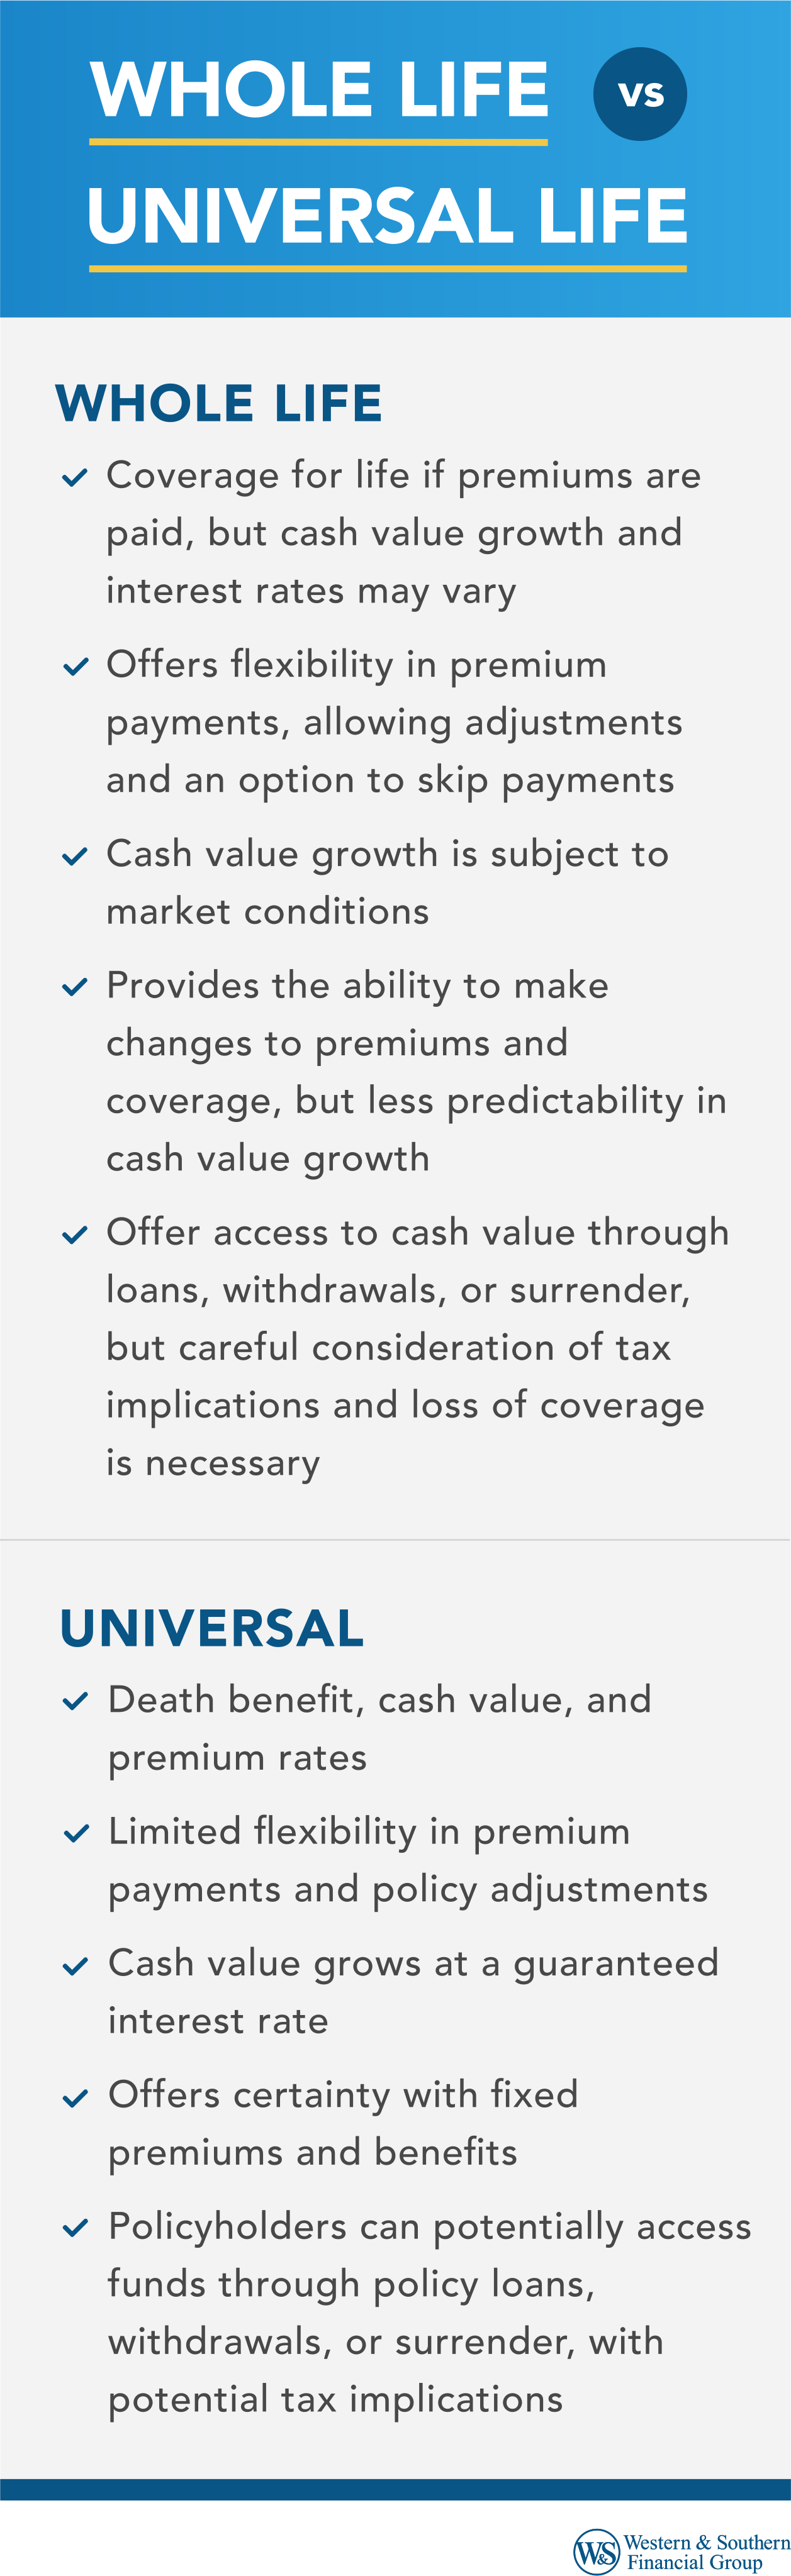
Whole life and universal life insurance share several similarities, but they differ in predictability and flexibility.
Whole life insurance is generally more predictable. Policies have a guaranteed interest rate, guaranteed cash values and a guaranteed death benefit for any given year. These features are set when the policy is issued and generally cannot be reduced unless you withdraw money from the contract. To maintain these guarantees, you must pay your scheduled premiums as agreed.
Universal life insurance generally offers more flexibility. Depending on the policy, you may be able to reduce or occasionally skip premium payments without losing coverage. For example, someone with irregular income might pay more into the policy when funds are available and reduce or pause payments during periods with less income.
However, this flexibility comes with considerations. If the policy runs out of cash value, it could lapse, potentially resulting in a loss of coverage and tax consequences.
Universal life also does not guarantee its crediting rate in the same way as whole life insurance. The policy may earn more or less than expected, which can affect how much you need to pay in premiums over time.
Is Whole Life or Universal Life Protection Better?
The right type of life insurance depends on your needs, comfort with risk and other personal factors. Understanding how each policy works can help you determine which type of coverage may fit your situation.
If you prefer predictability, whole life insurance might be a good fit. You generally know in advance how much you'll pay in premiums and how the policy's cash value will grow over time. As long as required premiums are paid, the policy provides a guaranteed death benefit.
If you prefer more flexibility, universal life insurance might make sense. Depending on the policy, you may be able to adjust or occasionally skip premium payments when cash flow is tight. However, universal life insurance generally offers less predictability than whole life insurance. If the policy does not have enough value to cover its costs, you may need to make additional premium payments to keep the coverage in force.
Accessing Cash Value From Whole Life Insurance
There are several ways to access the cash value of a whole life insurance policy while you're alive. For example, you may be able to borrow against the policy, generally without creating an immediate taxable event.
Policy loans should be used carefully. Loans accrue interest and can reduce the death benefit your beneficiaries receive. If a loan causes the policy to lapse, you could also lose coverage and potentially face tax consequences.
You may also be able to access cash value through withdrawals or by surrendering the policy. Surrendering ends your coverage and may have tax implications. Withdrawals may also result in taxable income if you take out more than you've contributed to the policy over the years.¹
Accessing Cash Value From Universal Life Insurance
The cash value of a universal life insurance policy may also be available through loans, withdrawals or surrender.² Similar tax considerations and potential effects on coverage can apply.
Before taking money from a universal life policy or surrendering it completely, consider how the transaction could affect the policy's cash value, death benefit and continued coverage.
The Bottom Line
Ultimately, the decision between universal life insurance versus whole life insurance depends on your needs. Evaluate the pros and cons of each option. Consider consulting with a financial professional to help determine what may be better for you and your family. Equipped with guidance and the information above, you may find yourself in a better position to make a well-informed choice.
Footnotes
- Withdrawals may be subject to charges, withdrawals of taxable amounts are subject to ordinary income tax, and, if taken before age 59½, may be subject to a 10% IRS penalty.
- Interest is charged on loans, they may generate an income tax liability, reduce the Account Value and the Death Benefit, and may cause the policy to lapse.