The personal finance realm impacts every part of life but is rarely taught. When you learn some of these skills, managing your finances can become more accessible and benefit you.
Defining Personal Finance
Personal finance refers to how you manage your money. It covers several areas that can affect your current finances and future goals, including:
- Income: Money you receive from work, investments or business activities.
- Savings: Money set aside from your income for future expenses or emergencies.
- Discretionary expenses: Nonessential spending on things such as entertainment and dining out.
- Investments: Money put into assets such as stocks, bonds or real estate with the goal of earning a return or increasing in value.
- Debt: Money you borrow and must repay, such as loans and credit card balances.
- Retirement accounts: Accounts such as 401(k)s and IRAs designed to help you save for retirement while offering certain tax benefits.
Personal finance also includes several broader areas of money management:
- Banking: Services provided by banks, including savings accounts, loans and payment processing.
- Retirement: Preparing financially for the time when you stop working, often through savings, pensions and retirement accounts.
- Real estate: Land and buildings that may be purchased for personal use or as an investment.
- Taxes: Required payments to the government on income, goods and certain activities that help fund public services and infrastructure.
- Estate planning: Preparing for the transfer of assets after death, including through wills and trusts.
With so many areas to consider, managing personal finances can feel intimidating. However, learning about personal finance can make the topic easier to understand. As you build your knowledge, you may find it easier to set individual or family goals, pay down debt and increase retirement savings.
Your finances can affect many parts of your life, including how much you save, the interest rates you receive on loans and when you may be able to retire. Building your personal finance knowledge can help you make more informed decisions over time.
Why Is Personal Finance Important?
Personal finance affects how you manage your money and cash flow. It can influence decisions such as whether you can purchase a home, the interest rates you receive on loans and when you may be able to retire. We face financial decisions every day. Some are simple, such as deciding whether to buy lunch at work. Others are more complex, such as preparing an estate for future generations.
Managing your finances, maintain a good credit score and limiting debt may make it easier to work toward your goals. Building financial literacy can also help you better understand your options and make informed decisions about your money.
Understand Your Baseline
A good first step in managing your money is understanding your current financial situation.
Establishing a baseline gives you a clear view of your finances. It can help you see where you may need to cut spending or whether you have extra money available to invest or save for retirement.
A spreadsheet or online tool can help you track your income and expenses. Review your numbers at the end of each month to understand your spending habits and prepare to set financial goals.
Set Financial Goals
Setting financial goals becomes easier once you have a clear picture of your current finances.
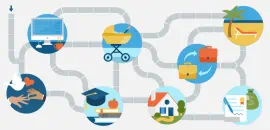
Common financial goals may include:
- Paying off credit card debt
- Paying off student loans or medical expenses
- Building an emergency fund
- Buying a home
- Saving for a wedding
- Saving for your child's college tuition
- Saving for retirement
- Saving for a vacation
Once you identify your goals, consider when you want to reach each one. Setting a timeline can help you decide how to account for your goals in your budget.
For example, a long-term goal like saving for retirement may span decades. A short-term goal, such as saving for a vacation next year, will have a much shorter timeline.
Stick to a Budget
Managing your money often starts with setting a budget. A budget can help you manage your income and expenses, track your goals and decide whether a purchase fits within your spending limits.
Getting started can be simple. Use your baseline spreadsheet or an online budgeting app to track your finances. These tools can help organize your spending and show when you may need to make adjustments.
Making small changes to your budget over time can help you manage your money more effectively and make progress toward your financial goals.
Build an Emergency Fund
According to the Federal Reserve, nearly 37% of Americans would need to borrow money or would be unable to cover an unexpected $400 expense.1 Another study by Bankrate found that 32% of Americans have less emergency savings than the previous year or no emergency savings at all.2
These numbers show why building an emergency fund can be an important part of your budget. Many experts suggest saving enough to cover about three to six months of expenses.
Your monthly living expenses may include:
- Mortgage or rent payments
- Monthly bills
- Food
- Gas
The goal is to have money available to financially survive an emergency, such as job loss, for a period of time. Consider keeping your emergency fund in a liquid account, such as a savings or money market account, so the money is easy to access when needed.
A rainy-day fund is similar to an emergency fund but is generally used for smaller unexpected expenses, such as new car tires or a vet bill.
Pay Down Debts
For some people, debt can be a significant barrier to reaching financial goals and saving for retirement. Carrying a large amount of debt can make it harder to work toward your goals and may also cause mental and emotional stress.
Learning how to manage your debt can support your overall financial health. Start by getting a complete picture of how much you owe. Seeing the total may feel overwhelming at first, but knowing the numbers can help you decide what to pay down first. From there, you can use your budget to set debt reduction goals.
Debt can take several forms, including:
Credit Card Debt
According to Experian, a major credit bureau, the average American has approximately $6,600 in credit card debt across multiple cards and an average credit utilization ratio of 28.3%.3
Credit card debt can become difficult to manage when balances are not paid off each month. Because some cards have high interest rates, making only the minimum payment can result in thousands of dollars in additional interest over time.
Keeping your credit utilization ratio below 30% is also important because a higher ratio may hurt your credit score.4 Paying down high-interest, short-term debt first can help keep it from becoming long-term debt.
Student Loan Debt
A recent study found that 42.8 million borrowers have federal student loan debt. Among those who still owe, the median amount of debt is between $37,000 and $44,000.5
Significant student loan debt can affect financial decisions ranging from buying a home to saving for retirement. Include student loan payments in your budget to help avoid missed payments and late fees.
Car Loan Debt
Experian found that the average American has just over $24,000 in outstanding car loan debt.6 Another report from CarEdge found that the average transaction price for a new car in 2026 was more than $49,000, a 3.4% increase from the previous year.7
A car loan is typically considered short- to medium-term debt, so include the payment in your monthly budget. If you have extra money available, consider putting it toward your car loan to help pay down the balance sooner.
The Consumer Financial Protection Bureau also provides information about borrowing and negotiating a car loan.8
Mortgage Debt
For many people, a mortgage is their largest expense and one of their longest-term debts. According to Experian, the average mortgage debt in 2026 was approximately $264,162.9
Because mortgage payments may account for a large portion of monthly income, include them when building your budget and emergency fund. Your emergency savings could cover several months of mortgage payments if you lose your job or are unable to work.
Refinancing your mortgage may also be an option that could reduce your monthly payment. The goal is to prepare for the long term and consistently pay down your balance. Over time, reducing debt can free up money for other goals and may help reduce financial stress.
Plan for Retirement
It is never too early or too late to start preparing for retirement. After decades of working, retirement can provide more time to enjoy a break and pursue new opportunities.
When you're younger, a key goal is building your retirement savings. As you get closer to retirement, you'll also want to create a budget that reflects your goals and expected lifestyle. For example, someone who plans to travel frequently during the early years of retirement may need a larger budget than someone who plans to spend more time at home with family.
A retirement budget can help you estimate how much you'll need each month to cover expenses and compare that amount with the income your savings may provide. Working with a financial professional or retirement planning service before you retire can also help you evaluate your retirement income and savings goals.
Save & Invest Your Money
Building savings over time can help you prepare for retirement. There are several ways to do this, including adding to your savings, investing in the stock market and contributing to retirement accounts.
As you create your ideal budget, look for opportunities to add to your savings each month. Even small contributions can add up over time. Compound interest and potential investment growth can make a significant difference over several decades, particularly for those who start investing earlier.
Ways to prepare for retirement include:
- Increase your Social Security benefits: Qualified retirees can claim Social Security benefits, which are paid monthly and make up a portion of retirement income for many Americans. Benefits are generally based on your highest 35 years of earnings. Adding one or two years of higher earnings could increase your Social Security benefit. According to USA Today, 47% of Americans are worried they won't have enough saved for retirement.10 The Social Security Administration offers resources to help you learn more.11
- Maximize your 401(k): Many employers offer retirement plans such as a 401(k). Traditional 401(k) contributions are generally made with pretax income, and withdrawals are typically subject to income taxes. Contributions are deducted from your pay before you receive your paycheck. Some employers also match employee contributions up to a certain percentage or dollar amount, which can help increase retirement savings.
- Open an IRA: Whether or not you have an employer-sponsored retirement plan, you can consider opening an individual retirement account (IRA). Some people with 401(k)s also use IRAs to increase their retirement savings opportunities. Once your account is established, you can allocate money from your budget toward contributions. Review your overall savings strategy each year and make adjustments based on your goals, investment performance and risk tolerance.
Focusing on your long-term goals and investment strategy can help you prepare financially for retirement.
Consider Your Insurance Needs
Insurance can also play a role in preparing for your financial future. Coverage such as life insurance, health insurance and long-term care insurance can affect your expenses throughout your life, particularly as you get older.
Many Americans receive health insurance through an employer. However, people who are self-employed or work for a small business may need to obtain health coverage on their own. If that's the case, you'll want to include those costs in your budget.
Life insurance is another type of coverage to consider. It provides a death benefit to your beneficiaries when you die. Depending on your family's needs, the death benefit could help cover expenses such as a mortgage, student loans, tuition or childcare. It may also help replace income or pay outstanding debts.
The cost of life insurance can vary based on several factors. According to The Zebra, more than half of Americans overestimate the cost of term life insurance by three times its actual price.12
As you create your budget, remember to include your insurance expenses. In addition to health and life insurance, consider costs for auto, homeowners or renters insurance, if applicable.
Stay on Top of Taxes & Estate Planning
It may be difficult to think about what will happen to your financial resources after you die, but estate planning can be an important part of preparing for the future.
Estate planning allows you to decide how assets such as your home, life insurance and savings accounts will be transferred to your loved ones. One common approach is creating a will that outlines your wishes for your assets.
A financial professional and attorney can help you understand options for protecting and transferring your assets. They can also provide guidance on tax considerations related to your assets during your lifetime and after your death.
Taxes are another important part of managing your finances. Because you need to prepare for tax season each year, consider including taxes in your regular financial checkup.
You can also look for ways to maximizing your deductions, such as contributing more to your 401(k) or other tax-advantaged accounts, including a health savings account.
Budget for Buying a Home
Real estate is another area to consider when managing your personal finances. Buying a home is a major financial decision with long-term costs, so it is important to understand how homeownership fits into your budget.
As you prepare to buy a home, use your budget to review your income and debts, determine how much you can spend and identify ways to save for a down payment. You should also account for the additional costs that come with buying and owning a home, including:
- Closing costs
- Taxes
- Bank fees
- Upkeep and maintenance
A qualified real estate agent and mortgage broker can also help answer questions about the homebuying process.
Review Finances Consistently
Your budget is a living document. As your finances change, your budget should change with them. Consider reviewing it every three to six months and making adjustments as needed. You may also want to revisit it after a major life change.
Regularly reviewing your finances can help you stay on track and develop a habit of preparing for the future. Before making a large purchase, consider how it fits within your budget and whether it would require taking on additional debt.
Setting clear, actionable goals during these reviews can also help you manage your finances and track your progress over time.
Keep Learning Personal Finance Basics
Learning how to manage money is an ongoing process. As you build your knowledge and become more comfortable with your finances, you can adjust your approach and learn about more complex topics over time.
Building a strong foundation of personal finance knowledge can help you make more informed financial decisions. To continue learning, consider reading personal finance articles, taking courses or working with a financial professional, depending on your needs and learning style.
A financial professional can also provide guidance as you continue learning and working toward your financial goals.
Sources
- Federal Reserve. "Report on the Economic Well-Being of U.S. Households." https://www.federalreserve.gov/consumerscommunities/sheddataviz/unexpectedexpenses-table.html
- Bankrate. "Bankrate’s 2026 Annual Emergency Savings Report." https://www.bankrate.com/banking/savings/emergency-savings-report/
- Experian. "Average Credit Card Debt Increases Just 0.6% to $6,659 in 2026." https://www.experian.com/blogs/ask-experian/state-of-credit-cards/
- CreditKarma. "What is credit card utilization and how does it affect your credit scores?" https://www.creditkarma.com/credit/i/credit-card-utilization-and-your-credit-score
- Education Data Initiative. "Student Loan Debt Statistics." https://educationdata.org/student-loan-debt-statistics
- Experian. "Average Auto Loan Debt Grew 2.1% to $24,909 in 2026." https://www.experian.com/blogs/ask-experian/research/auto-loan-debt-study/
- CarEdge. "The Average New Car Is $49,000 — America’s Top-Sellers Cost $7,000 Less." https://caredge.com/guides/new-car-price-update-march-2026
- Consumer Financial Protection Bureau. "Auto Loans." https://www.consumerfinance.gov/consumer-tools/auto-loans/
- Experian. "Average US Mortgage Debt Increases to $264,162 in 2026." https://www.experian.com/blogs/ask-experian/how-much-americans-owe-on-their-mortgages-in-every-state/
- USAToday. "Half of workers fear they will never fully retire." https://www.usatoday.com/story/money/personal-finance/2026/10/10/american-workers-fear-no-full-retirement/91902169007/
- Social Security. "Retirement benefits." https://www.ssa.gov/retirement
- The Zebra. "Life Insurance Statistics." https://www.thezebra.com/resources/research/life-insurance-statistics/