Retirement can change the way debt fits into your household finances. A payment that feels manageable while you are working may take up more of your income once earnings are replaced or supplemented by Social Security, pensions, retirement accounts or other sources.
Looking at debt and retirement together may help you understand how monthly obligations, taxes and retirement savings could affect your options.
Why Debt Matters as Retirement Gets Closer
Carrying debt does not necessarily prevent retirement. It does, however, create monthly payments that use part of your available cash flow.
U.S. households carried about $18.8 trillion in total debt at the end of the second quarter of 2026, including about $1.26 trillion in credit card debt.1 Those figures include consumers of many ages, not retirees specifically. Still, they provide context for how common consumer debt remains in household finances.
For someone approaching retirement, the more useful question may be how debt payments fit alongside housing costs, health care, taxes, everyday expenses and other priorities.
Start With Your Cash Flow
One way to look at your debt when considering retirement is to estimate how much of your expected income may already be committed each month.
Consider reviewing:
- Monthly payment: How much income goes toward each debt?
- Interest rate: Is it fixed, variable or promotional?
- Repayment period: How long could the obligation continue?
- Type of debt: Is it a credit card, mortgage, auto loan, personal loan or education loan?
- Available cash: How much flexibility would remain after regular expenses?
For example, $600 in monthly debt payments represents $7,200 of annual cash flow. That does not mean an immediate payoff is preferable. It simply shows how much income is already committed before other expenses enter the picture.
This type of review may be especially useful when housing costs, dependent children, caregiving or other family expenses remain part of your household finances.
Different Types of Debt Create Different Trade-Offs
Not all debt works the same way.
| Debt Type | What to Consider | Potential Limitation |
|---|---|---|
| Credit cards | Interest rate, minimum payment and whether the rate is promotional |
Interest charges may continue while an amount remains unpaid |
| Personal loans | Rate, monthly payment and repayment period |
Fees and total borrowing costs vary |
| Mortgage | Rate, remaining term and monthly payment |
Taxes, insurance and maintenance continue even after the mortgage ends |
| Auto loans | Rate, payment and remaining term |
Vehicle ownership costs continue after the loan is repaid |
| Education debt | Whether the debt is federal or private |
Repayment options vary by loan type |
Credit card companies may offer low or 0% introductory rates for debt transfers. These promotional periods are temporary and fees may apply.
Debt consolidation may also combine several obligations into one payment. However, a lower monthly payment does not always mean a lower total cost. A longer repayment period, fees or a different interest rate may affect how much you ultimately pay.2
Paying Debt vs. Adding to Retirement Savings
Another common personal finance question is whether extra cash might go toward debt or retirement savings.
There is no single interest-rate threshold that answers this question for every household. Factors may include:
- The interest rate on the debt
- Available cash for unexpected expenses
- Employer retirement contributions
- Taxes
- Investment risk
- Time until retirement
- Your broader investment strategy
Paying down debt provides a known reduction in future interest costs when the debt carries interest. Investment returns, by comparison, are uncertain and may be positive or negative. The source of money used for a payoff also matters.
If you want to compare the two approaches using your own numbers, our Pay Off Debt or Invest Calculator may help you estimate how different assumptions could affect the outcome.
Using Retirement Accounts to Pay Debt
Taking money from retirement accounts may create tax consequences, especially when distributions occur earlier in life.
Traditional individual retirement account (IRA) withdrawals are generally taxable. However, if a traditional IRA includes nondeductible contributions, part of a distribution may be nontaxable.
Roth IRA rules differ. Qualified Roth IRA distributions are generally tax-free, while other distributions follow separate ordering and tax rules.3
Early withdrawals may create additional tax consequences. For example, the taxable portion of an IRA distribution before age 59½ is generally subject to an additional 10% tax unless an exception applies.3
SEP IRA and SIMPLE IRA distributions may also have tax consequences, so the specific type of retirement account matters when considering whether to use retirement savings for debt management.
For example, if you withdraw $20,000 from a taxable retirement account to repay debt, the withdrawal could also create an income tax liability. If taxes are withheld from the distribution, less than $20,000 would be available for the debt.
Debt, Delayed Retirement & Social Security
Debt may also factor into decisions about how long you work.
Continuing to work may provide additional employment income and more time to address debt before relying more heavily on retirement income. But delayed retirement involves more than debt. Health, job availability, caregiving, housing costs and personal priorities may all matter.
Social Security timing adds another consideration. Retirement benefits may begin as early as age 62, but starting Social Security before full retirement age reduces the monthly benefit. Delaying beyond full retirement age increases the monthly amount through delayed retirement credits until age 70.4
Debt does not determine when someone claims Social Security, but monthly obligations may be one part of the broader cash flow discussion.
Credit Reports, Credit Scores & Debt Consolidation
Your credit report may also matter if you are considering refinancing or debt consolidation.
A credit score is generally based on information in your credit report. Scoring models may consider factors such as payment history, unpaid debt, account history, use of available credit and new applications for credit. Different models can produce different scores.5
When considering a new loan or credit offer, think about:
- Interest rate: How does it compare with your existing debt?
- Fees: Are there transfer or origination charges?
- Repayment period: Will the debt remain for longer?
- Monthly payment: Does it fit expected cash flow?
- Total borrowing cost: Could the new structure cost more over time?
Reviewing your credit report may also help you identify information that appears incorrect before refinancing or consolidating.
Debt Management & Family Expenses
Debt later in life may come from many sources. Credit cards and mortgages are only part of the picture.
Medical expenses, education costs, dependent children, housing costs and periods of lower income may all affect household finances. For that reason, effective debt management may involve more than simply paying the obligation with the highest dollar amount.
One way to look at the situation is to consider:
- Which debts carry the highest interest rates
- Which payments take up the most monthly cash flow
- How long each obligation is expected to remain
- Whether payments are fixed or variable
- How much cash would remain after a payoff
- Whether taxes could result from the source of the payoff
These comparisons are also part of broader financial literacy and personal finance decision-making. The approach that fits one household may not fit another.
When Debt Becomes Harder to Manage
If debt payments become difficult to fit within your income, you may want to review your options before the situation becomes more difficult. These could include contacting creditors about available payment arrangements, working with a not-for-profit credit counselling service or considering whether debt consolidation fits your circumstances.
For more serious debt problems, bankruptcy law may provide another path. Chapter 7 bankruptcy may discharge certain qualifying debts, although some debts are not dischargeable. Chapter 13 generally allows eligible individuals with regular income to repay all or part of their debts through a court-approved repayment plan, typically over three to five years.6
Because bankruptcy can have significant legal and financial consequences, you may want to discuss your circumstances with a qualified bankruptcy lawyer before deciding whether one of these approaches fits your situation.
Pros & Cons of Paying Debt Before Retirement
| Potential Benefit | Potential Limitation |
|---|---|
| Fewer monthly payments may improve cash flow |
A large payoff may reduce available cash |
| Paying interest-bearing debt sooner may reduce future interest charges | Using retirement accounts may create taxes |
| Lower fixed expenses may make budgeting more flexible | Money used for debt is no longer available for other goals |
| Paying down revolving debt may reduce credit use | Credit score effects vary by scoring model and credit profile |
| Fewer obligations may simplify household finances | Some debt may fit within expected retirement income |
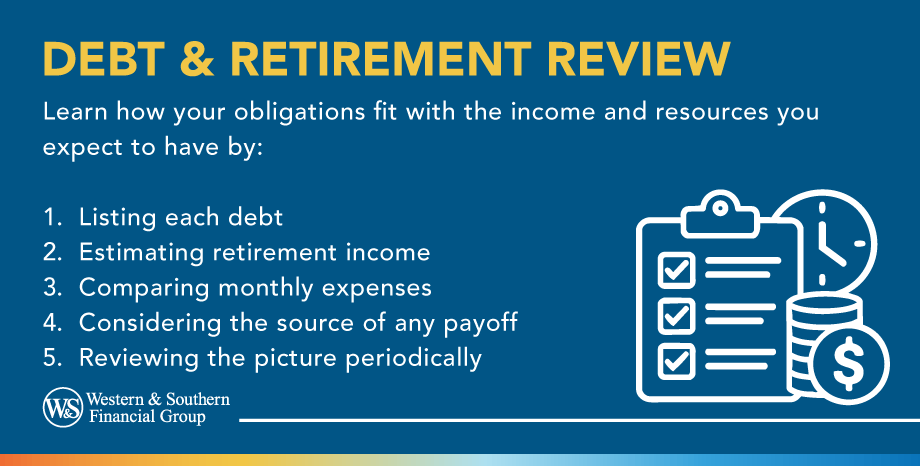
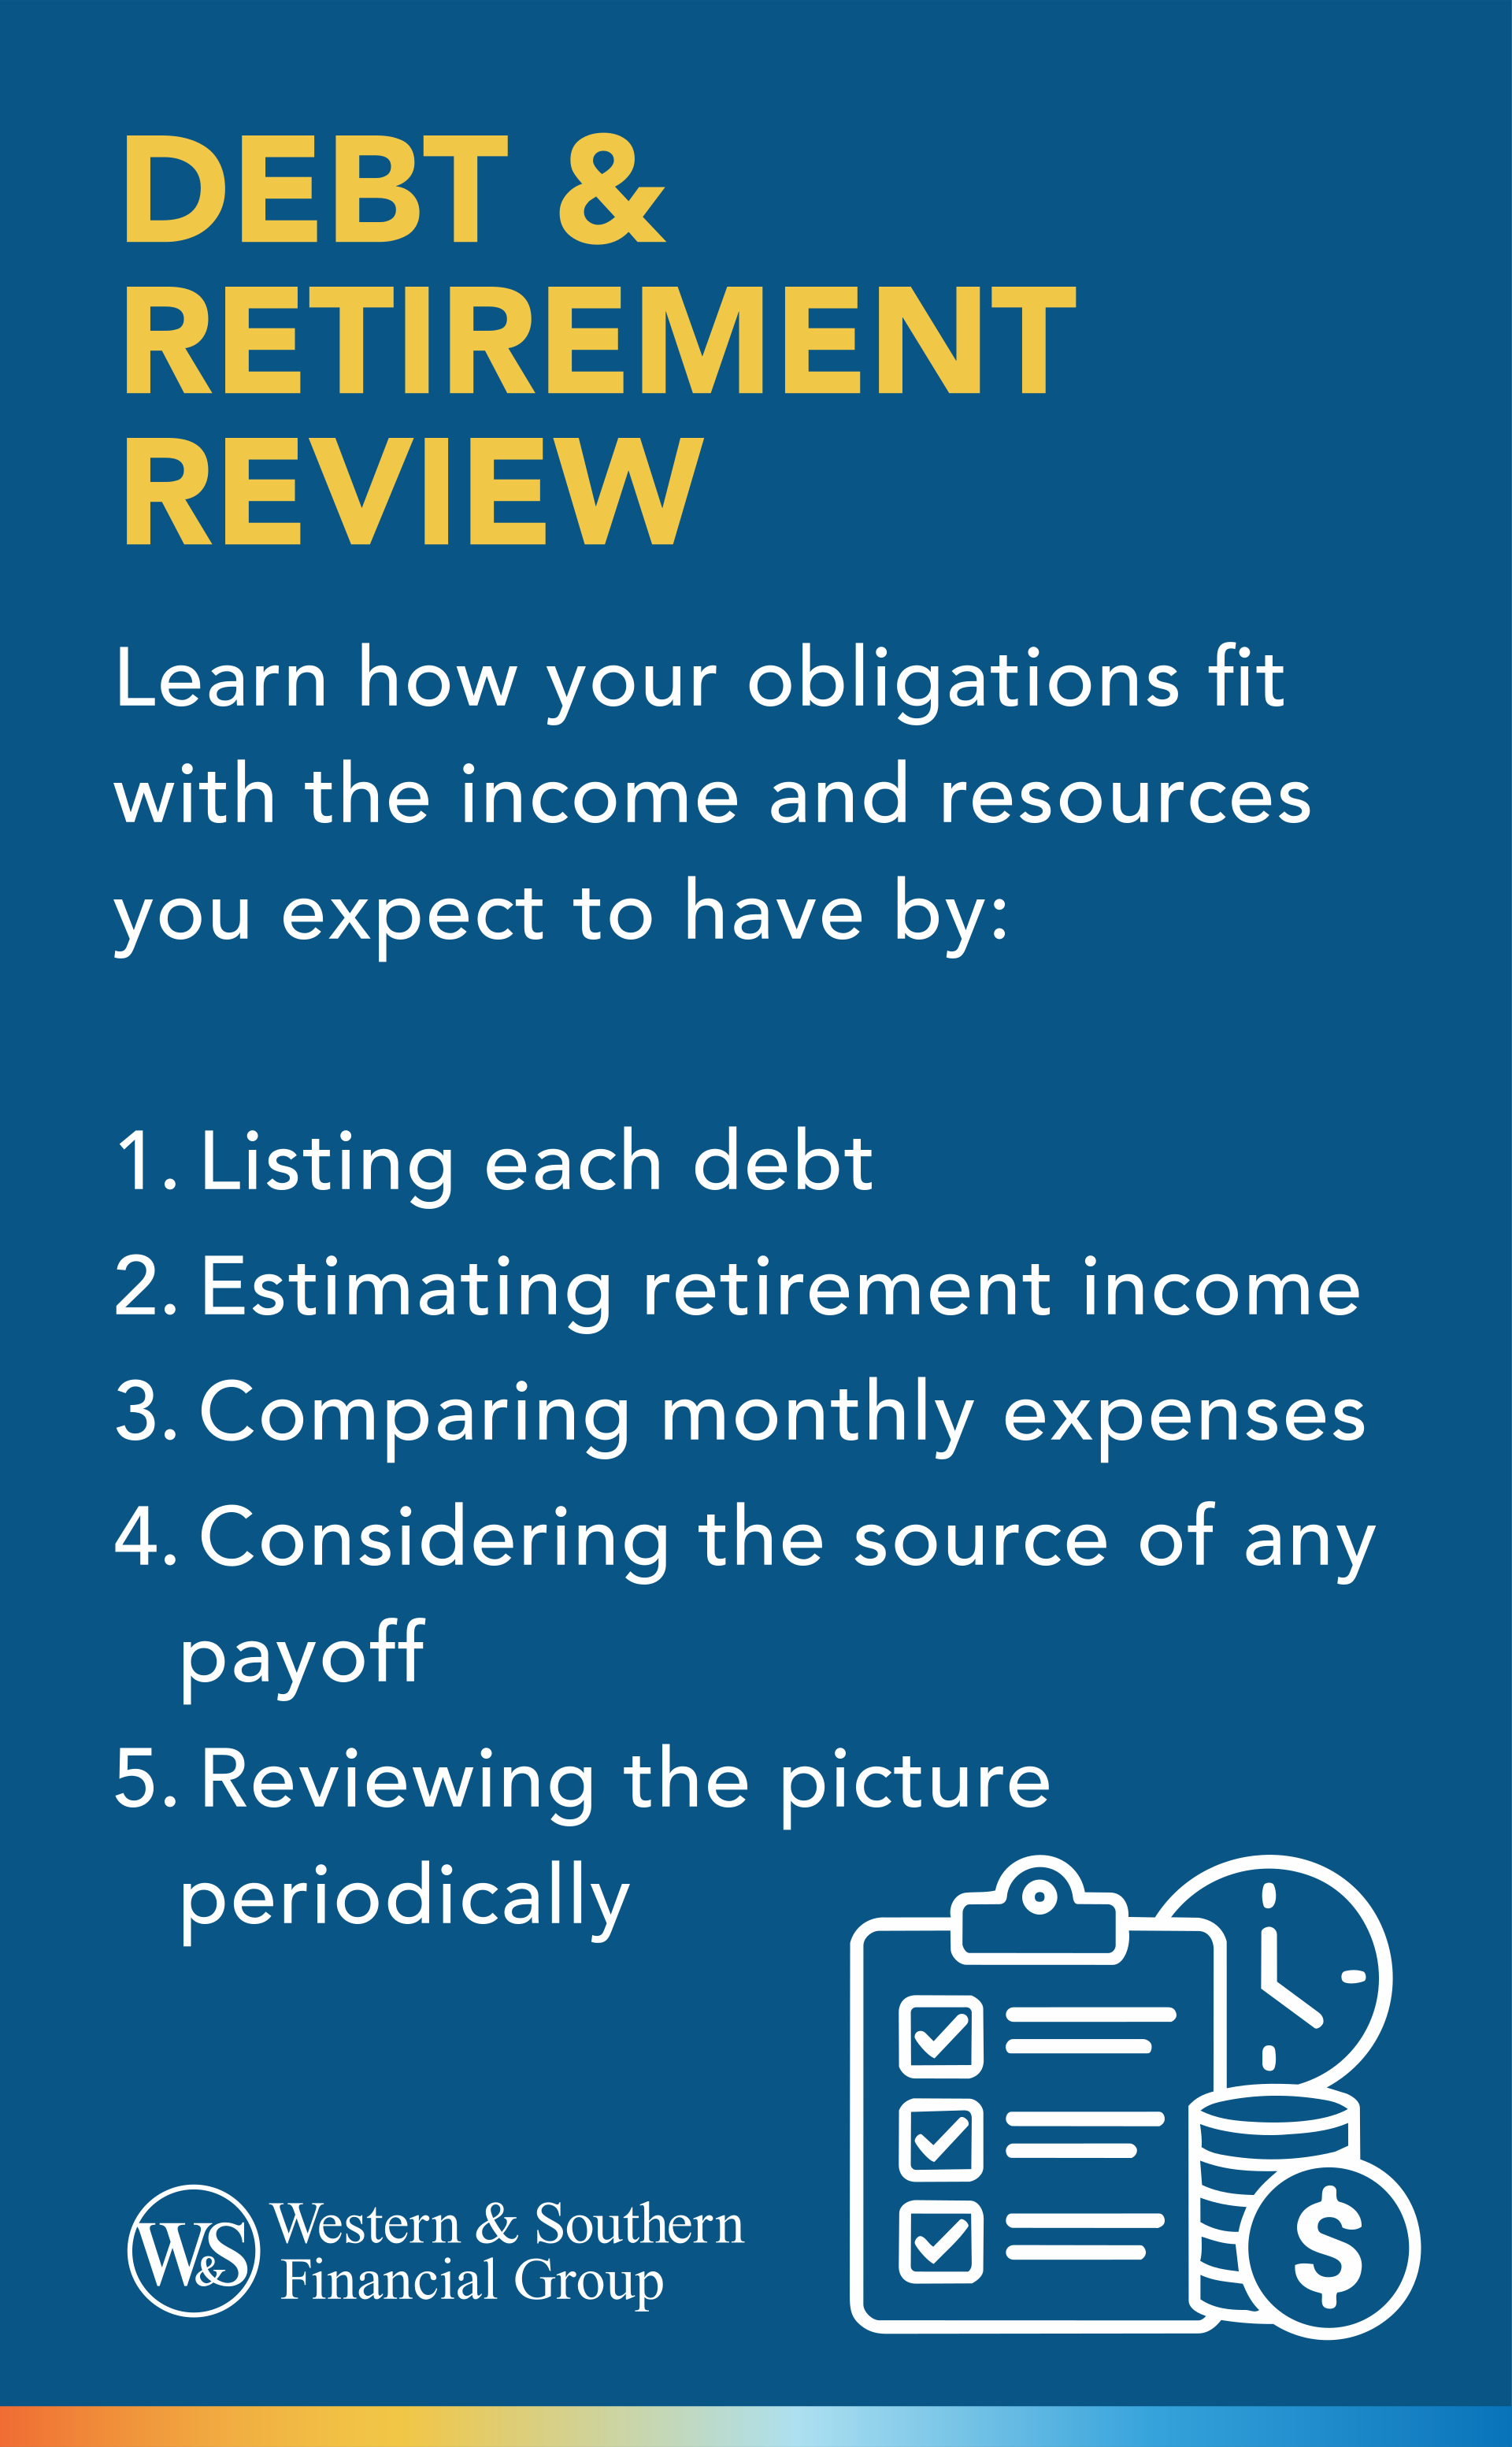
A Simple Debt & Retirement Review
Rather than relying on a universal debt-free rule, consider reviewing five areas:
- List each debt. Note the amount owed, monthly payment, interest rate and repayment period.
- Estimate retirement income. Include Social Security, pensions, employment income and retirement accounts.
- Compare monthly expenses. Look at debt alongside housing, health care, food, taxes and transportation.
- Consider the source of any payoff. Taxes may matter if money comes from a retirement account.
- Review the picture periodically. Changes in income, expenses or interest rates may change the trade-offs.
The goal is not to reach a particular debt number. It is to understand how your obligations fit with the income and resources you expect to have.
Conclusion
Debt may affect monthly spending, retirement savings and the amount of income available for other expenses. But the amount you owe is only one part of the picture.
Looking at interest rates, repayment terms, taxes, available cash and expected income together may provide a clearer view of how debt fits into retirement.
Before using retirement savings for a large payoff, consider how taxes and early withdrawal rules could affect the amount available to you.
See how small steps today could lead to smarter retirement choices. Get My Free Financial Review
Sources
- Household Debt Balances Decreased Slightly; Credit Card Delinquency Transition Rates Remained Steady. https://www.newyorkfed.org/newsevents/news/research/2026/20260811
- What do I need to know about consolidating my credit card debt? https://www.consumerfinance.gov/ask-cfpb/what-do-i-need-to-know-if-im-thinking-about-consolidating-my-credit-card-debt-en-1861/
- Publication 590-B (2025), Distributions from Individual Retirement Arrangements (IRAs). https://www.irs.gov/publications/p590b
- You Can Receive Benefits Before Your Full Retirement Age. https://www.ssa.gov/benefits/retirement/planner/applying2.html
- What Is a Credit Score? https://www.consumerfinance.gov/ask-cfpb/what-is-a-credit-score-en-315/
- Discharge in Bankruptcy - Bankruptcy Basics. https://www.uscourts.gov/court-programs/bankruptcy/bankruptcy-basics/discharge-bankruptcy-bankruptcy-basics