Choosing between a 529 plan and a Coverdell Education Savings Account (ESA) may feel like comparing apples and oranges. Both could help families cover future college expenses, but each comes with distinct rules, tax benefits, and contribution limits. If you're looking to understand which college savings plan might align with your family's goals, you're in the right place.
What Is a Coverdell ESA?
A Coverdell ESA, or Coverdell Education Savings Account, is a tax-advantaged investment account that helps families pay for qualified education expenses, including K-12 tuition expenses and college expenses. You can open one through financial institutions that offer self-directed investments, giving you access to a wide range of individual investment options like mutual funds, stocks, and bonds.
Contribution Limits
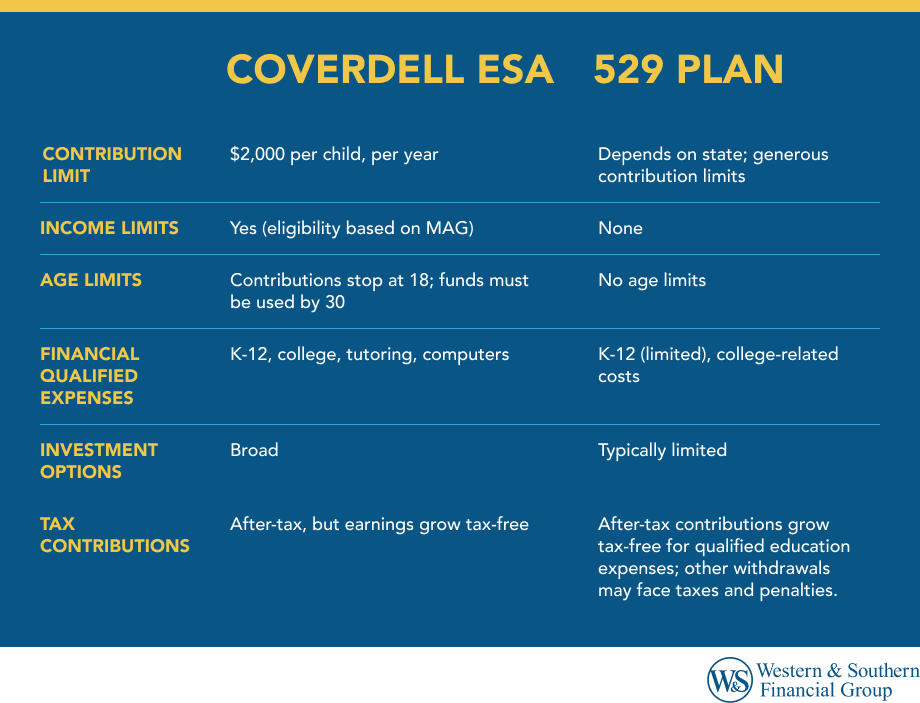
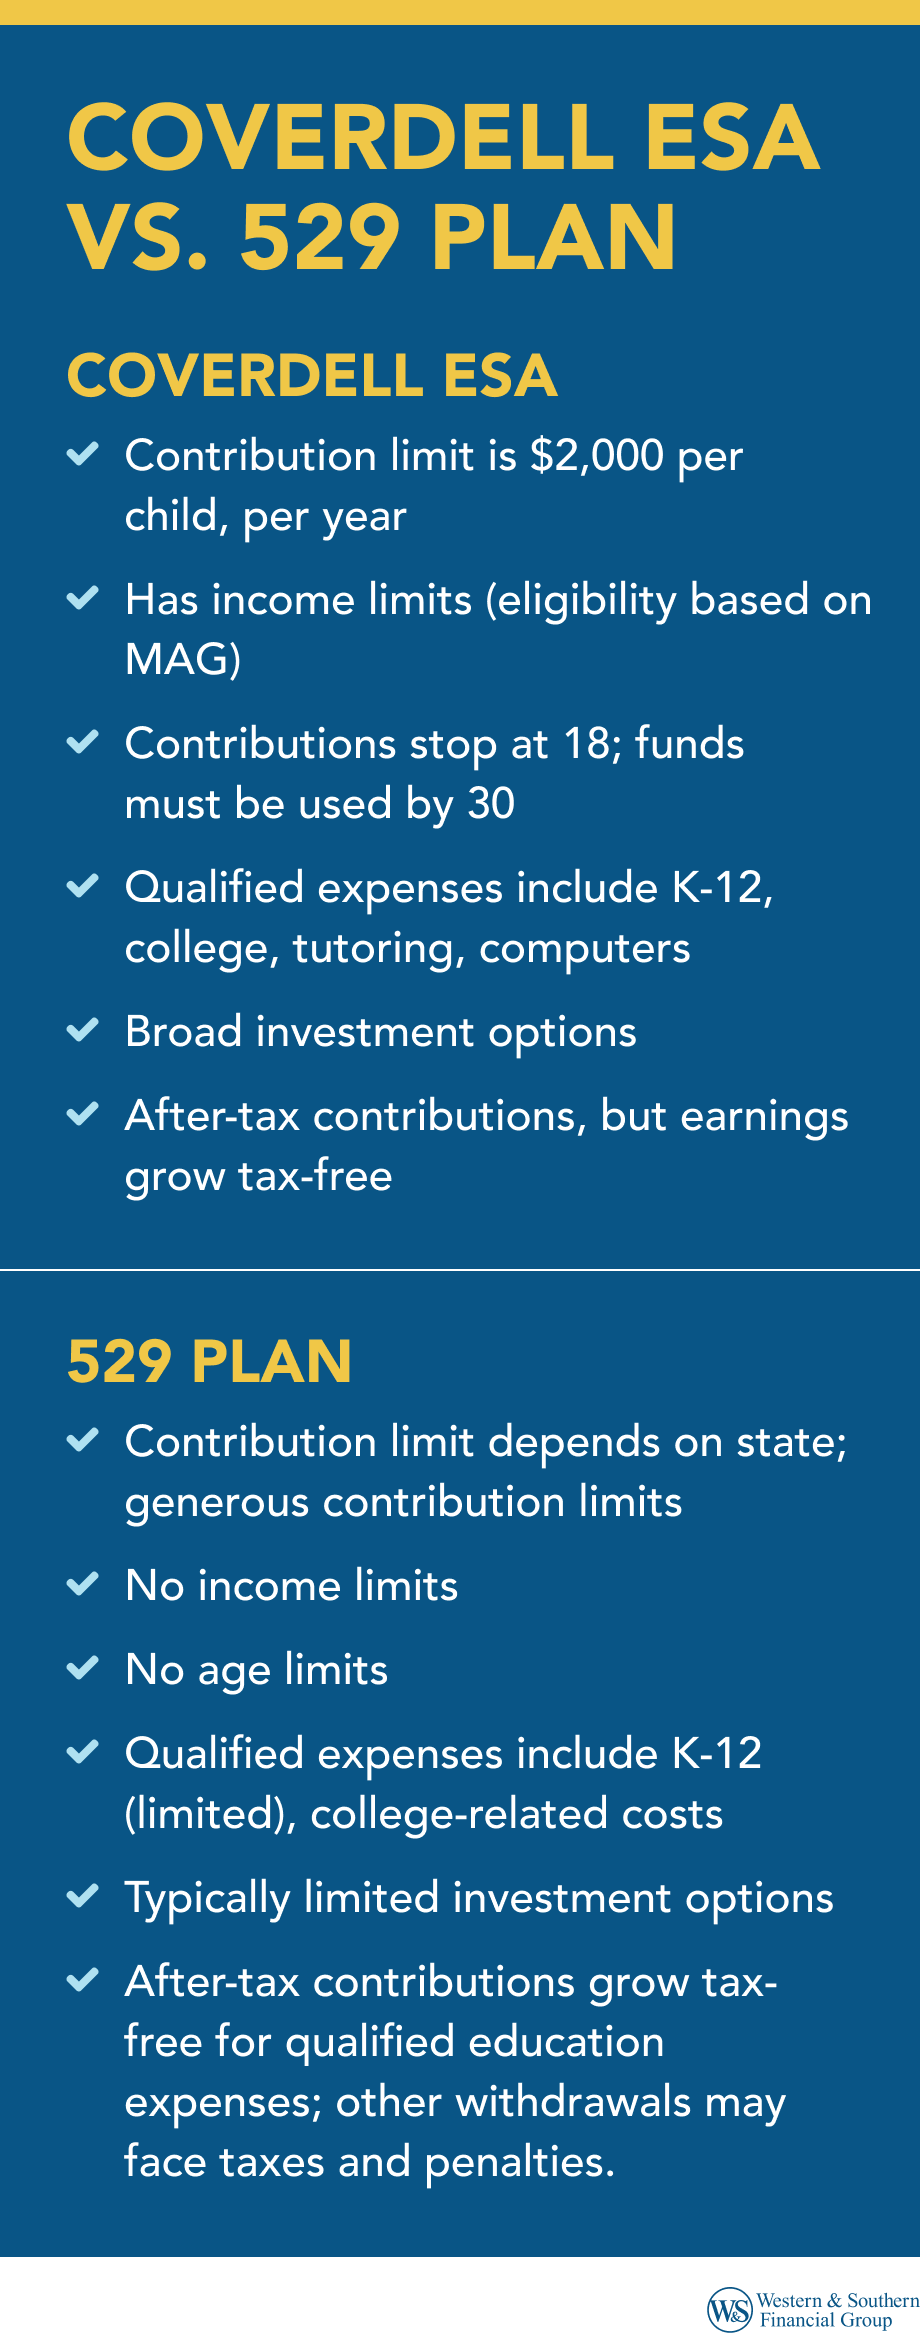
Coverdell ESAs allow for annual contributions up to $2,000 per beneficiary.1 These contributions are not tax-deductible, and the limit applies per child, not per contributor. Exceeding this annual contribution limit may result in an excess contribution and tax penalties if it is not corrected according to IRS guidelines.
Income Limits
There are limits for contributors based on income. Individuals earning more than $110,000 and married couples earning more than $220,000 generally cannot contribute, which may limit access for high-income households.2
Age Limits
Contributions can generally only be made until the beneficiary turns 18, unless they qualify as special needs beneficiaries, and the funds typically must be used by the time the beneficiary turns 30.
Qualified Expenses
One of the appealing features of a Coverdell ESA is its broad definition of qualified expenses. These accounts support a wide range of education-related costs. Qualified expenses include:
- Secondary school tuition
- Books and supplies
- Tutoring
- Higher education costs like college tuition, room and board, and computers
Investment Options
One distinguishing feature of the Coverdell ESA is the broad range of investment choices. Account holders can often select from mutual funds, stocks, bonds, and even alternative investments such as real estate investment trusts (REITs), depending on the custodian.
Tax Contributions and Benefits
Although contributions are made with after-tax dollars, the account grows tax-deferred. Withdrawals are tax-free if used for qualified education expenses. Non-qualified withdrawals may be subject to income tax and a 10% penalty.
Coverdell ESAs don’t provide deductions for contributions, but the tax-free growth can still offer significant value over time.
Pros & Cons
| Pros | Cons |
|---|---|
| Broad investment flexibility | Annual contribution limit of $2k per beneficiary |
| Covers wide range of qualified expenses | Contributors must meet income limits to be eligible |
| Tax-deferred growth and potential tax-free withdrawals | Contributions stop at age 18; funds must be used by age 30 |
| Can be used for more types of K-12 expenses than 529 plans | Account value can decrease based on market performance |
| Suitable for families seeking hands-on investment control | Cannot roll unused funds directly into a Roth IRA |
What Is a 529 Plan?
A 529 plan is a state-sponsored, tax-deferred education investment account designed to help you save for college tuition and other qualified educational expenses. These plans are accessible to all, regardless of income, and allow for contributions well above the Coverdell limit.
While the range of investment options is usually more limited, many states offer diversified, age-based investment portfolios that are managed by professionals. The account grows tax-deferred, and tax-free withdrawals are allowed when the funds are used for qualified expenses.
Contribution Limits
529 plans allow for significantly higher contribution limits, often over $300,000 total per beneficiary, depending on the state. There are no annual contribution caps federally, but gift tax rules may apply for larger contributions.
Age Limits
Unlike the Coverdell ESA, 529 plans generally have no age restrictions for using funds, and anyone can contribute. This flexibility can make a 529 plan suitable for multigenerational or long-term education savings, including for adult learners.
Qualified Expenses
The list of qualified expenses includes:
- College tuition and fees
- Room and board (if enrolled at least half-time)
- Books and supplies
- Up to $20,000 per year for K–12 tuition
- Some apprenticeship programs
- Up to $10,000 in student loan repayment (lifetime limit per beneficiary)
Investment Options
While 529 plans offer fewer choices than Coverdell ESAs, they are managed by experienced investment managers and often include age-based portfolios or target-date strategies. The principal value of a target date fund is not guaranteed at any time, including at or after the target date. These limited investment options appeal to families looking for a hands-off approach or those who prefer professionally guided investment decisions.
Tax Contributions and Benefits
Like the Coverdell ESA, 529 contributions are made with after-tax dollars. The account grows tax-deferred, and withdrawals are tax-free when used for qualified education expenses. Some states offer credits for contributions or deductions for contributions, depending on your residency and the plan chosen.
Contributions to 529 plans are considered gifts for tax purposes and may require filing a gift tax return depending on the amount contributed. In 2026, an individual can give up to $19,000 per recipient ($38,000 for married couples who elect to split gifts) under the annual gift tax exclusion. Gifts above this amount generally require filing a federal gift tax return.3
Pros & Cons
| Pros | Cons |
|---|---|
| High contribution limits ($300k+) | Few investment options; typically limited to state-selected portfolios |
| No income restrictions for contributors | May incur penalties and taxes on withdrawals used for non-qualified expenses |
| Tax deferred growth & potential tax-free withdrawals | Investment returns not guaranteed |
| Can be used for K-12 tuition (up to $20k per year), college, and more | Some states do not offer deductions or credits for contributors |
| Beneficiary can be changed or funds rolled into a Roth IRA | State rules vary; transferring plans may be complex |
| No limit for contributions or usage | Gift tax considerations for large contributions |
The performance of a 529 or Coverdell ESA is not guaranteed, and the value of your investment may decline depending on market conditions.
Additional Differences to Consider
Special Needs Planning: 529 & Coverdell
Coverdell ESAs come with age restrictions, generally allowing contributions only until the beneficiary turns 18, and requiring withdrawals by age 30. However, in certain cases the age limit can be waived for children with special needs.
529 plans do not impose age restrictions on contributions or distributions. They can be particularly useful for special needs beneficiaries who may have educational needs spanning a longer period.
Legacy Planning: Comparing the Long-Term Strategies
A 529 plan allows the account owner to change beneficiaries, helping families preserve educational savings for siblings, cousins, or even grandchildren. There is no federal lifetime contribution limit, although contributions are subject to overall educational need thresholds set by the plan.
Coverdell ESAs impose stricter limits on both contributions and usage timelines. The account must be used before the beneficiary turns 30, and it has a lower annual contribution cap. These factors make Coverdell ESAs less flexible as part of a multi-generational strategy.
Beyond College: The Expanding Definition of Qualified Education
Recent legislative changes have expanded what counts as qualified education expenses, and 529 plans have adapted accordingly. They now cover a range of costs beyond traditional college tuition, including K-12 tuition, certain apprenticeship programs, and even limited student loan repayment.
Coverdell ESAs have always supported expenses related to K-12 education. In this way, they offer more flexibility for younger students. However, the expanded utility of 529 plans has narrowed this gap considerably, making them increasingly competitive for families with diverse educational needs.
Avoiding Unused Savings: Managing Leftover Balances
Worried about unused college savings? Both account types offer some flexibility. With a 529 plan, you can change the beneficiary to another eligible family member or roll the balance into a Roth IRA under certain conditions. If none of these options are used, withdrawals are subject to income tax and a 10% penalty on investment income.
Rollovers from a 529 plan to a Roth IRA are subject to IRS rules and limitations. Consult a tax advisor to evaluate your eligibility and tax consequences.
Coverdell ESAs allow similar transfers to eligible family members, provided the new beneficiary is under 30. Otherwise, unused amounts withdrawn for non-qualified expenses may also incur taxes and penalties. Because of these nuances, families should consider potential fallback plans when selecting an account.
Final Thoughts
Both Coverdell ESAs and 529 plans offer unique features and tax benefits that could help you move toward your education savings goals. The right choice may depend on how you plan to use the funds, your income level, and how much control you want over your investment options.
You may want to consider your state's 529 plan or speak to a Registered Representative to determine how each plan fits within your broader investment strategy.
Sources & Footnotes
- Internal Revenue Service. "Topic no. 310, Coverdell education savings accounts." https://www.irs.gov/taxtopics/tc310
- Internal Revenue Service. "Publication 970 (2025), Tax Benefits for Education." https://www.irs.gov/publications/p970
- Internal Revenue Service. "Gifts & Inheritances 1." https://www.irs.gov/faqs/interest-dividends-other-types-of-income/gifts-inheritances/gifts-inheritances-1
- Fidelity. "How unused 529 assets can help with retirement planning." https://www.fidelity.com/learning-center/personal-finance/529-rollover-to-roth